Guides
Matching wrap and tint shop insurance to its real failure modes
Wrap and tint shop insurance mapped by failure mode: which policy answers which loss, where the gaps sit, and what to ask a broker before binding cover.
What to take away
- Work from failure modes to policies, not the other way around. The gaps show up immediately.
- The loss this trade is most exposed to, damage to a customer's paint, is the one general liability is least likely to answer.
- No premium figures appear here. Premiums depend on your state, your building, your payroll, and your claims history.
- Your refusal rule is a risk control. It reduces the frequency of the loss that hurts most.
- The wording decides everything. Ask for the wording, not for a summary.
The failure modes, and what answers each
Failure modes and what answers each
| What goes wrong | The policy usually involved | Where the gap tends to be |
|---|---|---|
| Film pulls clear coat off a repainted panel during removal | Care, custody and control, or a garagekeepers style cover | General liability commonly excludes property in your care |
| A customer vehicle is damaged while parked on your lot | Garagekeepers or a similar cover for vehicles in your care | Whether cover applies while the vehicle is unattended overnight |
| A customer trips in the waiting area | General liability | Usually covered, and usually the least of your problems |
| Fire or theft takes your film stock and tools | Commercial property | Whether stock is valued at cost or replacement, and whether film in transit is included |
| An installer is injured by a blade or solvent | Workers compensation | Arranged before the first hire, as your state requires |
| The bay is unusable after a fire and work stops | Business interruption | Whether the indemnity period is long enough to refit a bay |
| A wrap fails and the customer wants the job redone | Usually nobody. This is your own workmanship | Rework is a cost line, not an insured loss |
| A vehicle is damaged in transit on a road test or collection | Commercial auto, or a driving extension | Driving customer vehicles is frequently excluded by default |
| A design you printed infringes someone else's rights | Sometimes a media or advertising extension | Often narrow, and never a substitute for approvals in writing |
| Film installed does not comply with state law | Almost certainly nobody | This is a compliance failure, and it is managed rather than insured |
Read that table from the right hand column. The pattern is that the losses most specific to this trade are the ones a standard package handles least well.
Failure mode to policy map
What goes wrong
- Film pulls clear coat
- Care custody control
- Vehicle damaged on lot
- Garagekeepers
- Customer trips
- General liability
- Fire or theft of stock
- Commercial property
- Installer injured
- Workers compensation
- Bay unusable after fire
- Business interruption
- Wrap fails, redo
- Usually nobody
- Damage in transit
- Commercial auto
Policy
- Film pulls clear coat
- GL excludes property in care
- Vehicle damaged on lot
- Unattended overnight cover
- Customer trips
- Usually covered
- Fire or theft of stock
- Cost vs replacement
- Installer injured
- Before first hire
- Bay unusable after fire
- Indemnity period length
- Wrap fails, redo
- Own workmanship
- Damage in transit
- Driving often excluded
Gap
- Film pulls clear coat
- Vehicle damaged on lot
- Customer trips
- Fire or theft of stock
- Installer injured
- Bay unusable after fire
- Wrap fails, redo
- Damage in transit
The exposure that defines this business
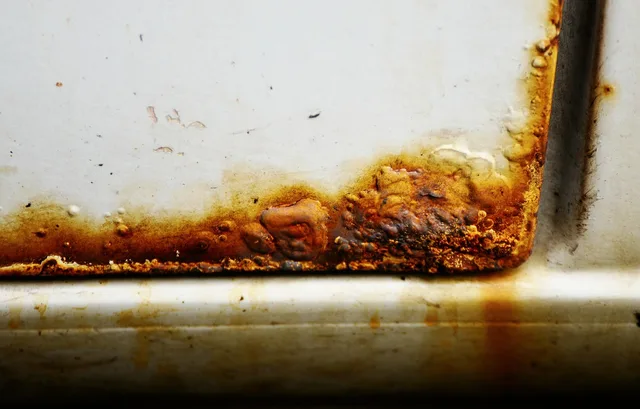
Vinyl adheres to whatever is on the panel. When it comes off, it takes the weakest layer. On a factory finish in good condition, that is fine.
On a repainted panel with unknown prep, failing clear coat, or over filler, the film can lift paint. The vehicle then needs bodywork, and the customer will look to you.
That single exposure should drive three decisions:
- A written refusal rule, applied by a named person, covering repainted panels of unknown history, peeling clear coat, and rust or filler under the area to be covered.
- An arrival inspection with photographs filed against the job number, every time, without exception.
- A written acknowledgment when a customer insists on proceeding against advice, signed before the vehicle is booked in rather than after the damage.
Insurance is the last line here, not the first. Underwriters price frequency, and the shop that controls this exposure with process is in a different position from the shop that does not. The inspection and refusal side of this sits in the licensing and compliance guide alongside the other things you have to hold on file.
Questions to put to a broker before binding
- Does the liability cover exclude property in my care, custody, or control, and if so what cover picks that up?
- Is a customer vehicle covered while parked on my lot overnight, and while being driven by my staff?
- Are removal jobs treated differently from installation jobs?
- How is my film stock valued, and is film held at a trade printer or in a van covered?
- What does the policy say about faulty workmanship, and what is excluded as rework?
- Does anything cover the cost of redoing a job, or is that entirely mine?
- What are my obligations after an incident, and how quickly must I report?
- What information do I have to keep for a claim to be considered?
Take notes and get the wording. A summary document is a sales aid; the wording is the contract.
Broker questions before binding
- Does liability exclude property in care?
- Is customer vehicle covered overnight?
- Are removal jobs treated differently?
- How is film stock valued?
- What does policy say about faulty workmanship?
- Does anything cover redoing a job?
- What are post-incident reporting obligations?
Why no numbers appear here
Premiums depend on your state, your building and its construction, and your payroll. They also turn on the vehicles you accept, your service mix, and your claims history.
A national page's figure would be wrong for almost every reader and used to judge a quote it has nothing to do with. Get three quotes on identical stated exposures, then compare wordings rather than prices.
The same is true of workers compensation, which is state-set and depends on your classification and payroll. That obligation begins at the first hire, and what that hire brings with it is covered in the hiring and training guide.
Risk controls that a broker will actually credit
- A documented arrival inspection with photographs.
- A written refusal rule with a named decision maker.
- A safe working practice covering solvent, blades, heat, and roof access. OSHA's guidance on safety management programs frames this as finding and fixing hazards before an injury or an inspection exposes them, which is the same logic an underwriter applies.
- Controlled storage of solvent and film, and a disposal route consistent with the EPA's automotive sectors regulatory information and your state agency's requirements.
- Accessible, safe customer areas. The Department of Justice's ADA guide for small businesses covers barrier removal in existing facilities, and the same review that finds an accessibility problem usually finds a trip hazard.
- Well-lit, uncluttered bays. The lighting that reveals a defect under film also prevents the accident that produces a claim, which is one reason the equipment and setup guide treats light as capacity rather than as decoration.
The registrations required before binding are in the what licenses a shop needs article.
A second site changes the whole exposure profile, which the expansion and market guide takes up.
Common questions
How much does insurance cost for a wrap and tint shop?
Nobody can say from a page. It varies by state, building, payroll, service mix, and history. Get quotes on identical stated exposures, and compare what each one actually covers.
Does my liability policy cover a customer's car while I am working on it?
Frequently not. Property in your care, custody, and control is a common exclusion in general liability, and it is exactly the property this business handles all day. Ask the question directly and get the answer in the wording.
Is a workmanship warranty an insurance product?
No. It is a promise you make and fund yourself. Keep it separate from the film manufacturer's material warranty, and price the expected rework into the job rather than hoping a policy absorbs it.
Do I need cover before I hire anyone?
You need liability and vehicle cover from the first customer. Workers compensation is a separate obligation that switches on with your first employee, and the rules are state-set, so confirm them with your state authority rather than with a national summary.